 UAE Trusted
Letter of Credit vs Bank Guarantee in UAE: Key Differences and How They Work
Not sure whether you need a Letter of Credit or a Bank Guarantee? Here's a quick look at how each works for UAE businesses.

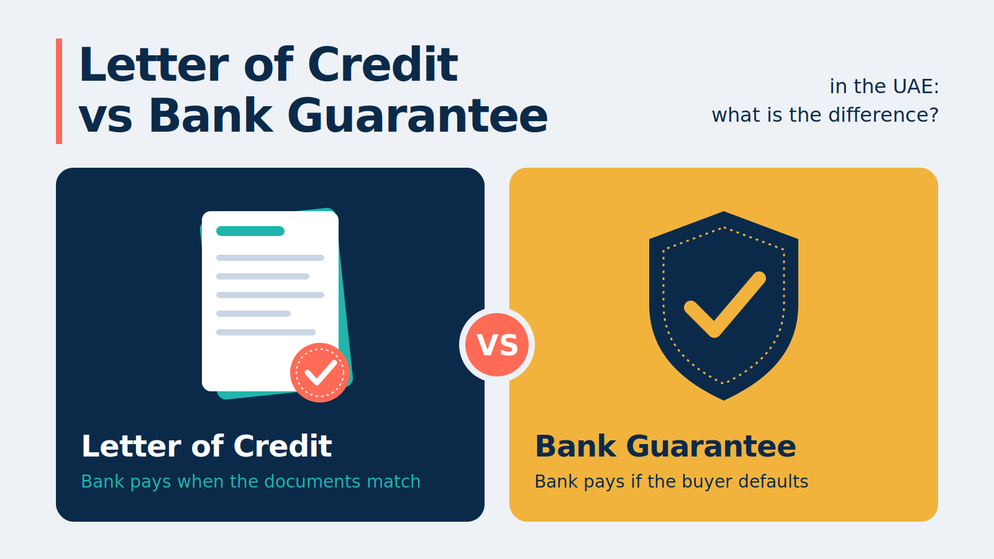
A Letter of Credit (LC) and a Bank Guarantee are both financial instruments provided by banks, but they serve different purposes in business transactions.
A Letter of Credit is mainly used to facilitate payment in a trade transaction. The bank makes payment when the beneficiary presents the documents required under the LC and those documents meet its terms.
A Bank Guarantee, on the other hand, provides financial security for a specific obligation. If the applicant does not meet that obligation and the beneficiary makes a valid claim under the guarantee, the bank may be required to make payment.
Understanding this difference helps businesses determine which instrument is more suitable for their transaction, whether the requirement involves trade payment, contractual performance, advance payment, or another financial obligation.
What Is a Letter of Credit?
A Letter of Credit (LC) is an undertaking issued by a bank on behalf of a buyer to make payment to a seller when the required documents are presented and comply with the LC terms.
In a typical transaction:
- Applicant: Buyer or importer
- Issuing bank: Buyer’s bank
- Beneficiary: Seller or exporter
- Advising bank: Bank that authenticates and advises the LC to the beneficiary
- Confirming bank: A bank that may add its own payment undertaking, where applicable
The documents may include a commercial invoice, transport document, packing list, certificate of origin, insurance document or other documents specified in the LC.
The bank generally examines the documents, rather than physically checking the goods or deciding whether the seller has completely performed the underlying sales contract.
Common Types of LCs
Sight LC: Payment is made after a complying presentation, subject to the LC terms.
Usance or Deferred-Payment LC: Payment is scheduled for a future date specified in the LC.
Confirmed LC: Another bank adds its own undertaking in addition to that of the issuing bank.Transferable LC: The credit specifically permits transfer to another beneficiary under the applicable rules.
What Is a Bank Guarantee?
A Bank Guarantee is an undertaking issued by a bank in favour of a beneficiary at the request of an applicant.
It is generally used to support a specific payment or performance obligation. If the beneficiary makes a demand that complies with the guarantee’s requirements, the bank may be required to pay up to the guaranteed amount.
In a typical structure:
- Applicant: Business whose obligation is being supported
- Issuing bank: Bank providing the guarantee
- Beneficiary: Party protected by the guarantee
- Advising bank: Bank that may authenticate and advise the guarantee
- Counter-guarantor: Bank involved in an indirect or international guarantee structure
Common Types of Bank Guarantees
- Bid or Tender Guarantee: Supports obligations during a tender process.
- Performance Guarantee: Provides security for contractual performance.
- Advance Payment Guarantee: Protects an advance payment made to the applicant.
- Payment Guarantee: Supports a specified payment obligation.
- Retention Guarantee: May be used instead of retaining cash under certain contracts.
Letter of Credit vs Bank Guarantee
| Point | Letter of Credit | Bank Guarantee |
| Main purpose | Supports payment in a trade transaction | Supports a payment or performance obligation |
| Typical applicant | Buyer or importer | Contractor, supplier, buyer, tenant, borrower or other obligated party |
| Typical beneficiary | Seller or exporter | Employer, project owner, customer, supplier, authority or other protected party |
| Point | Letter of credit | Bank Guarantee |
| Payment trigger | Complying presentation of documents required by the LC | Complying demand and supporting documents required by the guarantee |
| Main risk addressed | Payment risk in a commercial transaction | Non-performance, non-payment or another specified obligation |
| Common ICC rules | UCP 600, when incorporated | URDG 758, when incorporated |
| Document focus | Commercial and transport documents | Demand, beneficiary statement and documents specified in the guarantee |
| Typical nature | Payment mechanism | Contingent security |
How a Letter of Credit Works
1. Buyer and seller agree the transaction
The parties agree the price, delivery terms, documents, payment timing and other commercial conditions.
2. Buyer applies for the LC
The buyer approaches its bank with the required transaction details and beneficiary information.
3. Bank issues and advises the LC
The issuing bank sends the LC through an advising bank, where applicable.
4. Seller reviews the terms
The seller checks whether it can meet all documentary requirements before shipping the goods.
5. Documents are presented
After completing the transaction, the seller presents the required documents within the specified time.
6. Documents are examined
The relevant bank examines the presentation against the LC terms and applicable rules.
7. Payment or discrepancy handling
If the presentation complies, payment is handled according to the LC. If discrepancies exist, the transaction may require correction, waiver or another permitted solution.
How a Bank Guarantee Works
1. Parties define the obligation
The applicant and beneficiary agree the guarantee amount, purpose, validity and required wording.
2. Applicant approaches the bank
The business submits the relevant contract, beneficiary information and requested guarantee terms.
3. Bank reviews the application
The bank considers the applicant, available facility, security or margin requirements, transaction and guarantee wording.
4. Guarantee is issued
The bank issues the guarantee directly or through another bank depending on the transaction structure.
5. Applicant performs the obligation
The guarantee remains available during its stated validity period.
6. Demand or expiry
If a complying demand is made, the bank assesses it against the guarantee terms. If no valid demand is made before expiry, the guarantee ends according to its terms.
When Should a UAE Business Use an LC?
An LC may be appropriate when payment against specified trade documents is the main requirement.
It can be useful when:
- Buyer and seller are in different countries.
- The parties have limited trading history.
- The seller wants bank-backed payment assurance.
- The buyer wants payment linked to specified documents.
- The transaction involves international shipment of goods.
The LC should be carefully drafted so that the required documents are practical and consistent with the actual transaction.
When Should a Business Use a Bank Guarantee?
A Bank Guarantee may be appropriate when the main requirement is security for contractual performance or a defined payment obligation.
It may be used for:
- Tender or bidding requirements
- Performance obligations
- Advance payments
- Contractual payment obligations
- Retention arrangements
- Certain project and supply contracts
The guarantee wording is particularly important because the beneficiary’s ability to make a demand depends on the conditions stated in the instrument.
Documents UAE Banks May Request
Requirements vary between banks and depend on the applicant and transaction. Commonly requested information may include:
- Valid trade licence and company documents
- Shareholder and beneficial-owner information
- Authorised signatory details
- Financial information and bank statements
- Existing banking or trade-finance facility details
- Sales contract, purchase order or project agreement
- Applicant and beneficiary details
- Requested amount, currency and expiry
- LC or Bank Guarantee wording
- Details of goods and shipment for an LC
- Security, margin or counter-indemnity documents where applicable
Providing consistent information across the contract, application and supporting documents can help reduce avoidable processing issues.
Important Terms to Check Before Issuance
Before requesting an LC or Bank Guarantee, businesses should carefully review:
Amount and Currency
Check the guaranteed or payable amount and whether it can be reduced or increased.
Expiry
Confirm the expiry date, presentation period and place where documents or demands must be presented.
Documents and Conditions
Make sure every required document or statement can realistically be obtained within the specified period.
Governing Rules
Check whether UCP 600, URDG 758, eUCP or another set of rules has been incorporated.
Charges
Clarify issuing, advising, confirmation, amendment, SWIFT, correspondent and other applicable bank charges.
Amendment and Cancellation
Understand whether amendments or cancellation require the consent of the beneficiary or other parties.
Compliance Requirements
Banks may review the transaction, counterparties, jurisdictions, goods and supporting documents as part of their compliance procedures.
Costs and Credit Limits
Both LCs and Bank Guarantees can affect a company’s banking limits because they create exposure for the issuing bank.
Depending on the bank and transaction, costs may include:
- Issuance commission
- Advising or confirmation charges
- Amendment charges
- SWIFT and correspondent-bank charges
- Document examination or discrepancy charges
- Extension or claim-related charges
- Cash-margin or collateral-related costs
Common Mistakes to Avoid
For Letters of Credit
- Including unclear or unnecessary documentary requirements
- Setting unrealistic shipment or presentation deadlines
- Failing to review the LC before shipment
- Assuming the bank checks the physical quality of goods
- Ignoring discrepancies in presented documents
For Bank Guarantees
- Accepting unclear or unsuitable demand conditions
- Keeping the guarantee valid longer than necessary
- Overlooking automatic-extension provisions
- Failing to include practical reduction or release terms
- Not understanding the applicant’s reimbursement obligation if the bank pays
LC and Bank Guarantee in the UAE: What Businesses Should Know
UAE businesses should treat an LC or Bank Guarantee as a financial instrument that needs to match the underlying commercial transaction.
The bank may consider the applicant’s financial position, facility availability, transaction purpose, counterparties, jurisdictions, goods and supporting documents before issuing the instrument.
A commercially agreed contract does not automatically mean that a bank will issue the requested instrument. Approval, pricing, limits, margin, security and compliance clearance remain subject to the relevant financial institution’s policies.
How Prolific Enterprises Can Assist
Prolific Enterprises FZE LLC assists UAE businesses with understanding trade-finance requirements, organising supporting documents and coordinating applications with relevant banks and financial institutions.
Depending on the business and transaction, support may include:
- Letter of Credit requirements
- Bank Guarantee requirements
- Trade finance facilities
- Invoice and receivables financing
- Working capital finance
- Other business-finance solutions
Prolific does not issue LCs or Bank Guarantees. These instruments are issued by eligible banks or financial institutions. Final approval, pricing, limits, security, compliance clearance and issuance remain subject to the relevant provider .Explore: Trade Finance Support in the UAE | Business Loan and SME Financing Support
Frequently Asked Questions
Is a Letter of Credit the same as a Bank Guarantee?
No. An LC is primarily a documentary payment mechanism, while a Bank Guarantee generally provides security for a payment or performance obligation.
Does an LC guarantee the quality of goods?
No. Banks generally examine the documents required by the LC rather than physically inspecting the goods.
Can a Bank Guarantee be called without proving the entire contractual dispute?
It depends on the wording of the guarantee. Under an on-demand structure, a complying demand and required documents may be sufficient under the applicable terms.
Do LCs and Bank Guarantees require collateral?
Not necessarily. Requirements vary by bank, applicant, transaction and available credit facility. A bank may require cash margin, collateral, counter-indemnity or other support.
Can an LC or Bank Guarantee be amended?
Yes, subject to the instrument, applicable rules and required approvals or consents.
Does Prolific Enterprises issue LCs or Bank Guarantees?
No. Prolific assists businesses with requirement assessment, document preparation and application coordination. The actual instrument is issued by the relevant bank or financial institution.
Disclaimer
This article is provided for general educational purposes only and does not constitute financial, legal, trade, tax, sanctions or credit advice. The operation of an LC or Bank Guarantee depends on its exact wording, applicable rules, governing law, underlying contract and the relevant financial institution’s policies.
Availability, pricing, limits, margin, security, compliance clearance and approval are subject to the relevant provider. Businesses should review the applicable terms and obtain professional advice where appropriate before entering into a transaction.
Speak With Prolific About Your Trade Finance Requirement
If your UAE business is considering a Letter of Credit, Bank Guarantee or another trade-finance facility, Prolific Enterprises can help you organise the requirement and supporting information before approaching a financial institution.
Phone: +971 54 147 3606
Email: reachus@prolificbizgroup.com
Website: prolificbizgroup.com