 UAE Trusted
Finance Approval Workflow in the UAE: A Step-by-Step Guide for Businesses
Slow approvals delay purchases and weaken financial control. This step-by-step guide explains the finance approval workflow in the UAE, from request initiation and manager review to budget checks, CFO authorization and payment, so your business can approve spending faster and stay audit-ready.

Every business reaches a point where money starts moving faster than one person can track. A supplier invoice arrives while the owner is travelling. A team member buys software on a company card. A payment goes out twice because two people each thought the other had approved it.
A clear finance approval workflow prevents these problems. For businesses in the UAE, where VAT, Corporate Tax and banking requirements all depend on accurate, well-documented transactions, it is also a practical compliance tool.
This guide explains what a finance approval workflow is, how it works stage by stage, which UAE requirements touch it, and how to build one that your team will actually follow.
What Is a Finance Approval Workflow?
A finance approval workflow is the defined path a financial request takes before it becomes a payment or an accounting entry. It answers four questions for every transaction:
- Who can request spending?
- Who reviews and approves it?
- What must be checked before money leaves the business?
- Where is the evidence stored afterwards?
You may hear it called an approval process, approval chain, or authorization flow. The terms overlap, but the idea is the same: no payment happens without the right people having reviewed it, and every decision leaves a trail.
Why It Matters for UAE Businesses
A structured approval process helps in four ways.
Control. Approvals reduce errors, duplicate payments, and unauthorized spending, whether accidental or deliberate.
Compliance. Valid tax invoices, accurate VAT returns, and Corporate Tax filings all rely on well-kept records. An approval step is a natural moment to check that documents are complete.
Speed. It sounds counterintuitive, but clear rules make approvals faster. When everyone knows who signs off on what, requests stop waiting in the wrong inbox.
Audit readiness. Auditors, banks, and investors want evidence of how decisions were made. A documented flow gives them that.
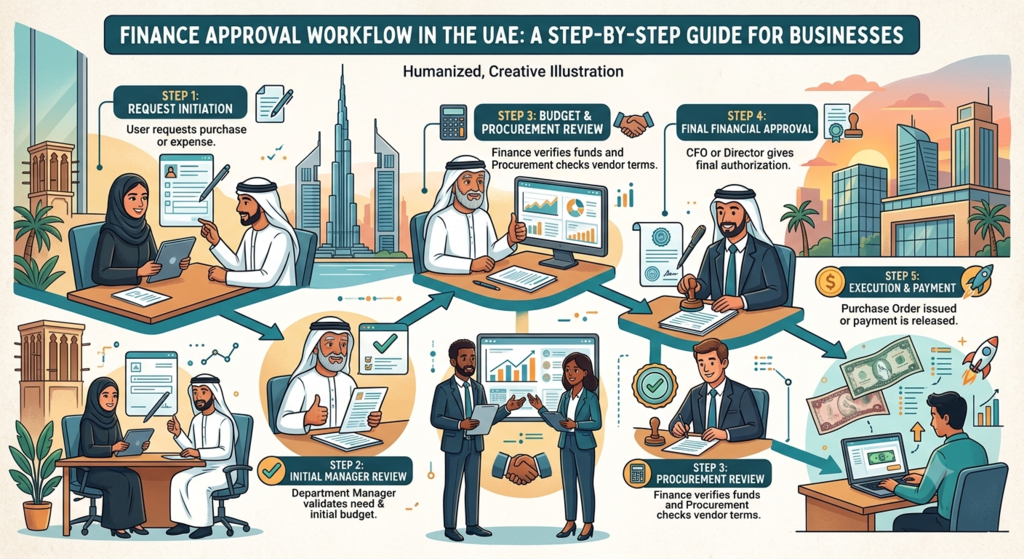
The Six Stages of a Finance Approval Flow
The exact steps vary by company, but most healthy workflows follow this sequence.
1. Request
Every transaction begins with a request: a purchase, an expense claim, a vendor invoice, or a payment instruction. The request should state what is needed, why, the supplier, the amount and currency, and any supporting document such as a quotation or contract.
Tip: Use a standard request form, even a simple one. Free-text messages are where details go missing.
2. Budget Check
Before anyone approves, confirm that the spending fits the plan. Is there budget available? Is it coded to the right department or project? This step catches problems early, when they are cheap to fix.
3. Manager Approval
The requester’s line manager or department head confirms the spending is genuinely needed and reasonable. This is the business-side approval: should we buy this?
4. Finance Review
The finance team checks the how. Typical checks include:
- Does the invoice match the purchase order and the goods or services received?
- Is the supplier’s information correct and the invoice free of duplicates?
- Is VAT treated correctly, and does the tax invoice contain the required details?
- Is the transaction coded to the right account?
5. Payment Authorization
An authorized person releases the payment. Good practice is to keep this separate from whoever requested or approved the spending, a principle known as segregation of duties. Where payments are made through the bank, the company’s bank signatory arrangements also apply.
6. Record Keeping
Once paid, the request, approvals, invoice, and proof of payment are filed together so anyone can trace the full story later. This stage is the one most often neglected and the one auditors ask about first.
UAE-Specific Points to Build In
The workflow itself is a business decision, but several UAE requirements shape what the finance review and record keeping stages should check.
VAT Tax Invoices
UAE VAT-registered businesses need valid tax invoices to support input VAT recovery and correct reporting. A tax invoice generally needs to show details such as the words “Tax Invoice,” the supplier’s name, address and Tax Registration Number (TRN), an invoice number and date, a description of the goods or services, the amount before VAT, the VAT rate and amount (in AED), and the total. Requirements differ slightly for certain cases, such as simplified invoices, so your finance team should check the Federal Tax Authority (FTA) guidance for specifics.
Building a “valid tax invoice?” check into the finance review stage helps prevent problems at VAT filing time.
Record Retention
Tax records must be kept for a set number of years, and the period depends on the tax and the type of record. VAT records have generally been subject to a five-year retention requirement, while Corporate Tax rules specify a longer period of seven years. Some property-related records have longer periods still. Many businesses simply apply the longer period across the board to keep things simple. Confirm the current rules with the FTA or a licensed advisor
Bank Signatories and Payment Controls
Your bank account mandate defines who is authorized to sign or release payments, and some accounts require more than one signatory. Your internal workflow should sit comfortably alongside these bank arrangements, not contradict them. Review both together whenever people join, leave, or change roles.
Payroll and the Wage Protection System (WPS)
For private-sector companies, salaries are paid through the Wage Protection System, which is overseen by the Ministry of Human Resources and Emiratisation (MOHRE) with the Central Bank. If payroll runs through your approval flow, build in a review of the payroll file before it is submitted, since an error affects every employee at once.
How Approval Limits Fit In (Without Copying Anyone Else’s)
Many businesses also define spending limits for each approver. There is no standard set by law. Each company chooses limits that fit its size, risk level, and industry. A useful way to decide is to ask:
- How much financial risk can each role comfortably carry?
- Which transaction types (routine expenses, new suppliers, one-off purchases, payroll) deserve closer review?
- Where should a second approver be required?
Common Mistakes (and How to Avoid Them
Approvals through chat messages and calls. A “yes” on a messaging app is easily lost. Record approvals in a system or a standard form.
One person doing everything. When the same person raises, approves, and pays, there is no check. Separate at least the approval and payment roles.
Skipping the document check. Paying first and collecting the tax invoice later often means chasing suppliers. Check documents before payment.
No backup approver. Holidays and travel are normal in any business. Name a delegate so the process does not stall.
Outdated authority lists. Former employees or changed roles left on approval lists are a real risk. Review the list whenever staffing changes.
Overcomplicating it. If every small purchase needs five sign-offs, people will find workarounds. Match the level of control to the level of risk
Manual vs Automated Approval Workflows
| Manual (email, paper, spreadsheets) | Automated (software-based) | |
| Setup | Quick and low cost | Needs configuration and onboarding |
| Visibility | Hard to see where a request is stuck | Real-time status and reminders |
| Audit trail | Scattered across inboxes and files | Automatically logged in one place |
| Error risk | Higher, especially as volume grows | Lower, with built-in checks |
| Best for | Very small teams with few transactions | Growing teams with regular approvals |
Finance Approval Checklist
Use this as a starting point and adapt it to your business.
Before approval
- Request is in writing with amount, purpose, and supplier
- Budget availability confirmed
- Supporting documents attached (quotation, contract, or PO)
During review
- Invoice matches order and delivery
- Valid tax invoice received, with correct TRN and VAT details
- No duplicate invoice or payment
- Correct account and cost center assigned
At payment
- Approved by the right person or people
- Payment authorized by someone independent of the requester
- Payment method and bank details verified
After payment
- Proof of payment filed with the request
- Records stored securely for the required retention period
- Exceptions or overrides noted and reviewed
Frequently Asked Questions
Is a finance approval workflow mandatory in the UAE?
The law does not prescribe a specific internal approval process for ordinary businesses. However, tax and accounting rules require accurate records, and a documented workflow is one of the most practical ways to meet them.
Who should be involved in the approval process?
Typically the requester, a line manager, the finance team, and an authorized payer. Smaller businesses may combine roles, but it is wise to keep payment authorization separate from requesting.
How long should we keep approval records?
Keep them at least as long as the tax and accounting records they support. For practical purposes, many UAE businesses follow the longest applicable period and confirm the current requirements with the FTA or their advisor.
Can a small business use a simple workflow?
Yes. A short form, a clear approver, and a consistent filing habit already deliver most of the benefit.
When should we automate?
When approvals start taking too long, requests get lost, or finding records for audits becomes difficult.
Final Thoughts
A good finance approval workflow does not need to be complicated. It needs to be clear, consistently followed, and reviewed as your business changes. Start by mapping your current process, mark where requests slow down or evidence goes missing, and fix those points first.
Rules and thresholds do change, so confirm tax and record-keeping requirements with the Federal Tax Authority or a UAE-licensed accountant before finalizing your own policy.
Disclaimer
This article is for general information and educational purposes only and does not constitute legal, tax, accounting, or financial advice. Regulations in the UAE may change, and their application depends on your company’s specific circumstances. Please consult the Federal Tax Authority (FTA), the Ministry of Human Resources and Emiratisation (MOHRE), your bank, or a UAE-licensed professional before making decisions or finalizing internal policies. The practices described are general guidance, not legal requirements.